Finance, economics and risk
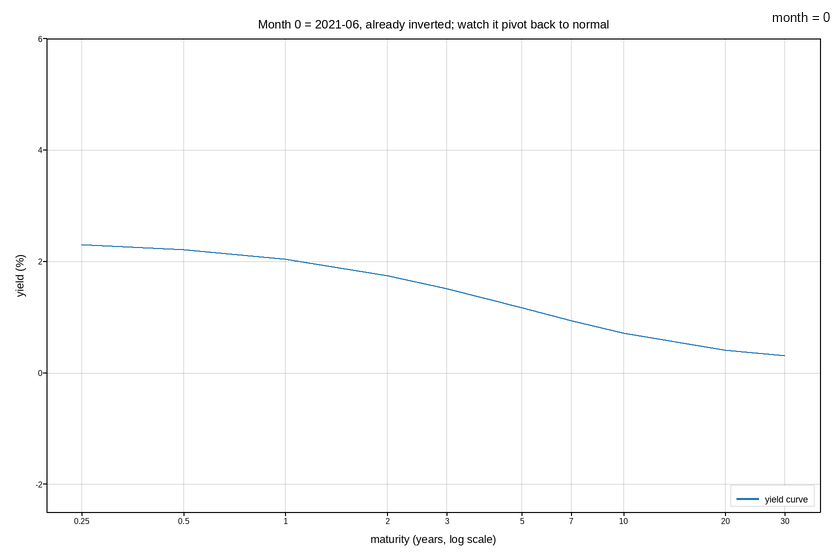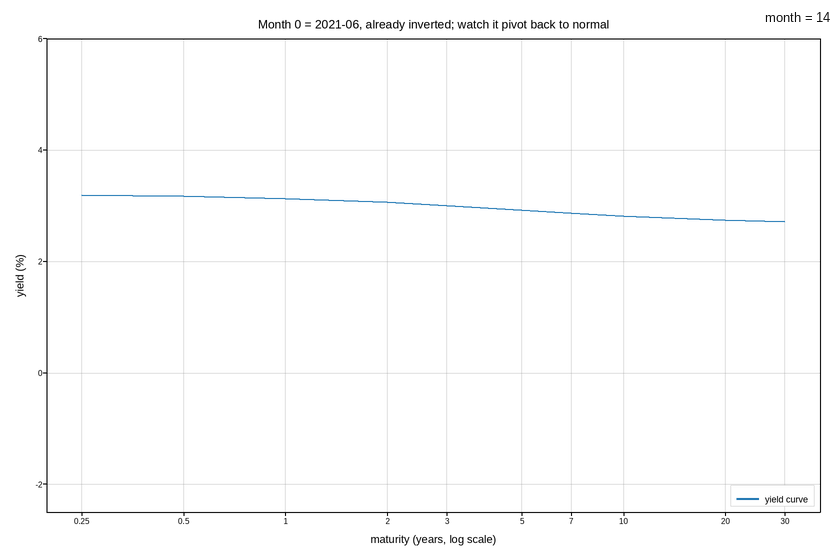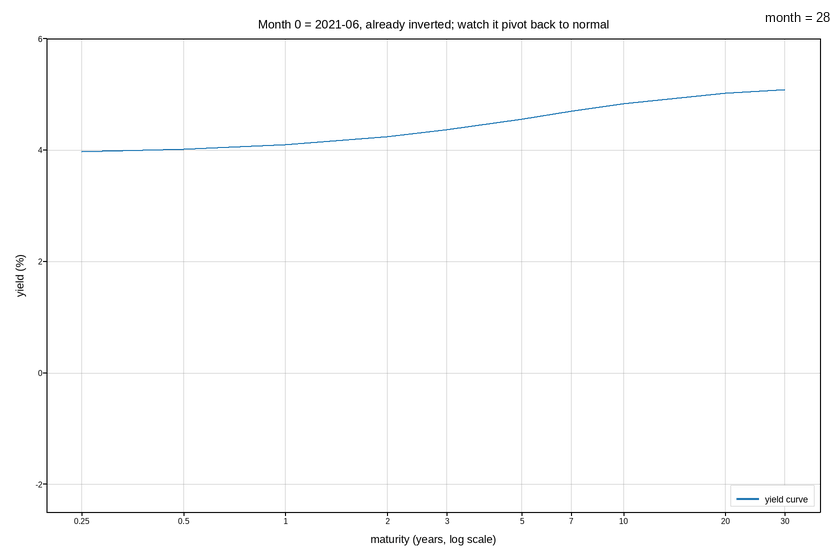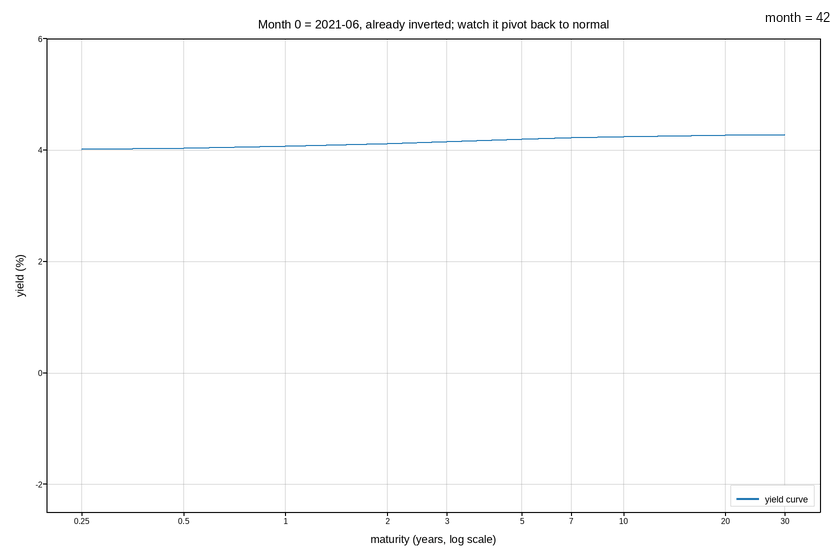
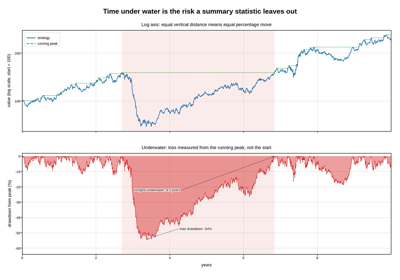
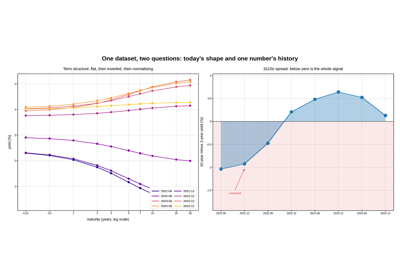
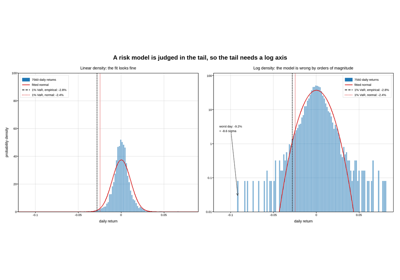
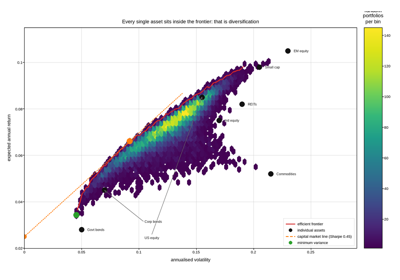
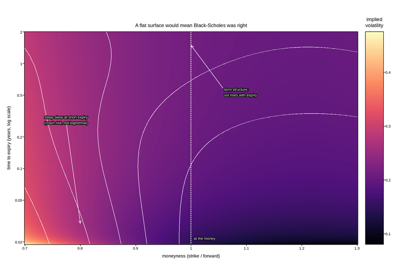
Drawdowns, term structures, return distributions, portfolio frontiers and option surfaces. Financial series are cumulative and multiplicative, so levels belong on a log axis and losses belong measured from the running peak; and the tail of the return distribution – not its centre – is the part a risk figure exists to show.
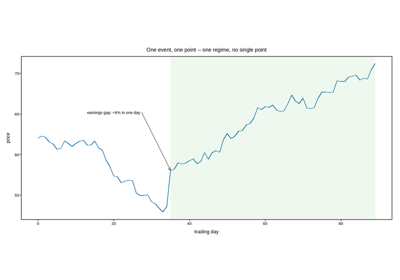
Annotating a price series: a single event vs. a whole regime
Annotating a price series: a single event vs. a whole regime